The practice is in Dallas, and the call is on video
Steven Palmieri works in Dallas as a Tax CFO, the Entrepreneur's CFO. The first check is still the person who spoke. A Comptroller letter can be the sentence that stung you. It may land the same week a partner called the card a mess, or the same month a preparer could not make the year agree. The letter makes the insult feel official. The role still picks the first artifact.
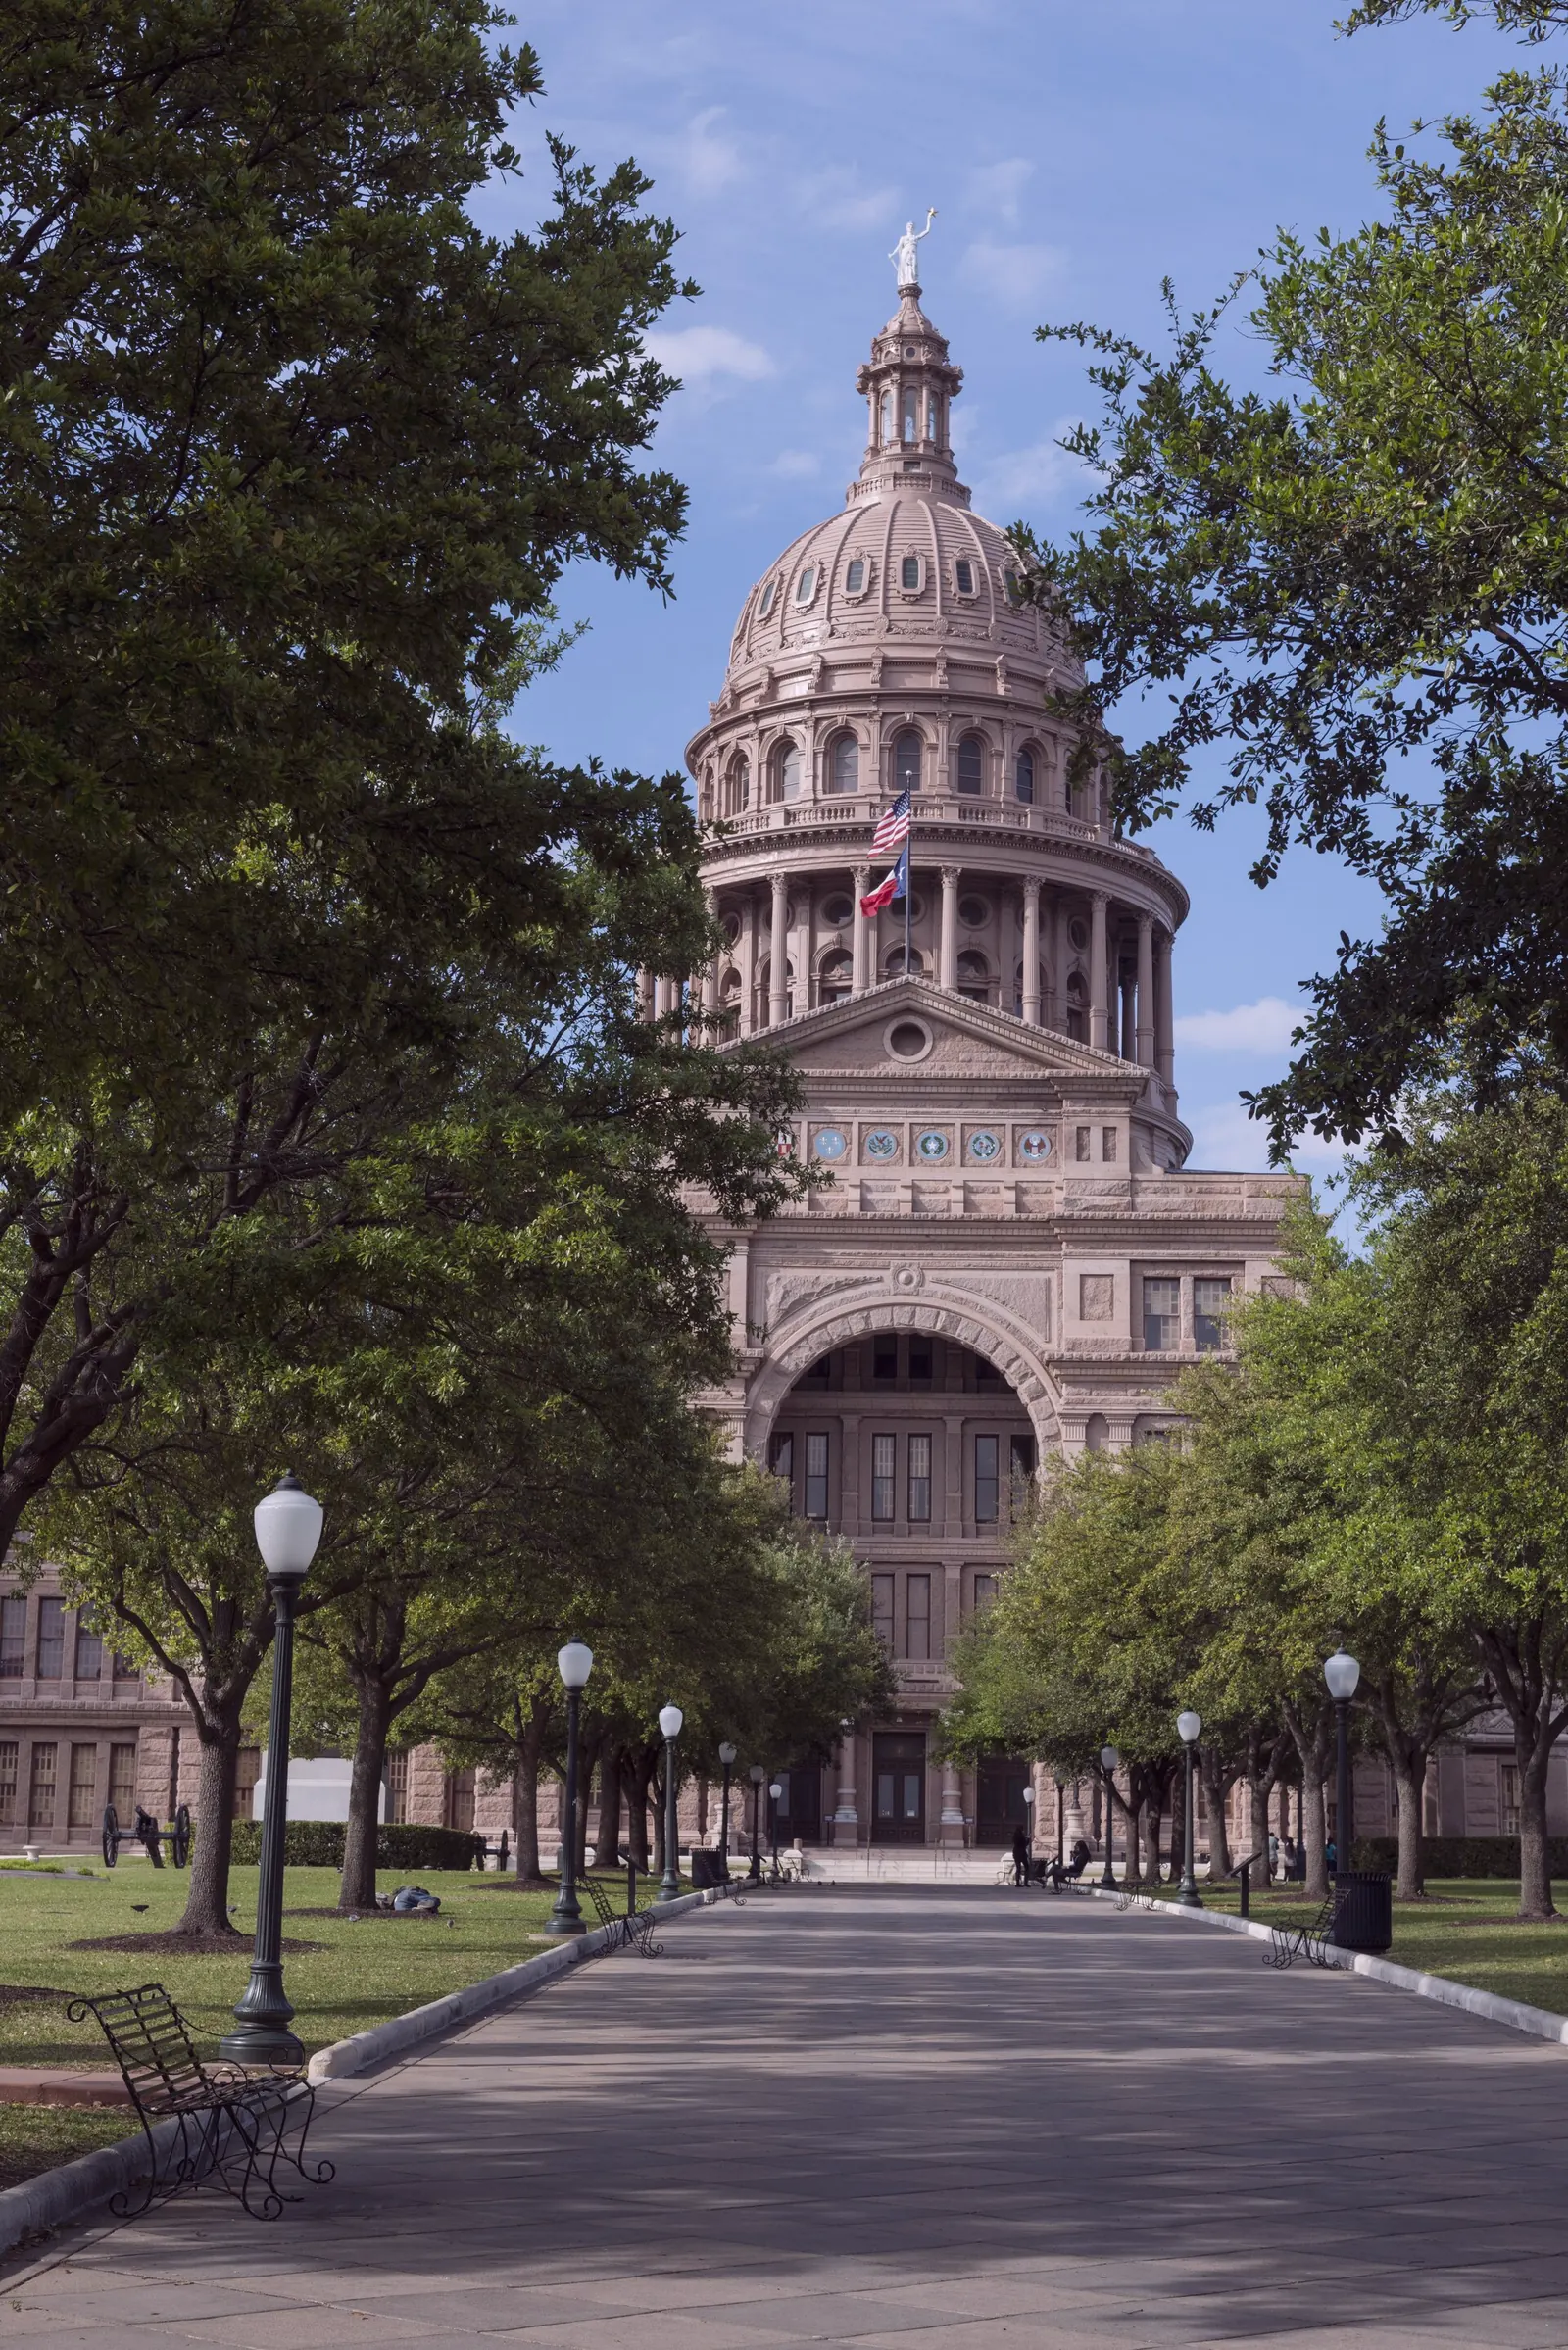
Owners anywhere in Texas reach that Dallas practice on a video call. We do not keep a room in the Hill Country, along the Gulf, or up in the Panhandle, and a weekend there is not a second shop. Call from any of those places and we are all Texans. Your statements are the file. The photograph is the capitol in Austin, the building where these rules are written. The close still happens on the pages you already have.
Who has to file the yearly privilege tax
When the letter is about franchise tax, the speaker is the state, and the question inside the letter is whether this company still holds the privilege of doing business here. That privilege is taxed once a year. Limited liability companies file, corporations file, a company with only one owner files, and a company that asked the IRS for S corporation treatment still files this state report. Someone who never organized a company, and who sells only under a personal name, generally has no franchise report to send. A general partnership made entirely of people, and never set up as a limited liability partnership, generally stays off the report too. An unusual structure gets answered from the Comptroller's own published list, which we read next to the sentence you were handed. We will not invent an extra kind of entity so a familiar box on the form has something in it.
What the tax rides on is margin, except where the company both qualifies for the shorter computation and actually picks it. Revenue is the pile every path starts from, and the state allows four ways through that pile. One way keeps seventy percent of revenue. Another takes revenue and removes what the goods cost. A third takes revenue and removes compensation. The fourth takes revenue and removes one million dollars. A company that sells services and nothing else often has no cost of goods the statute will allow, apart from industry exceptions the statute itself names. A combined group has to share one of those four ways across its members. The owner is the person who chooses, and the choice is real when the long form is the report that has to go in. We can lay the books out so that choice is visible. We will not make that choice on a tired Friday evening just so the report can leave Monday morning.
May 15 still wants the short paper
The annual report's day is May 15, and a weekend or a holiday slides that day to the following business day. In report years 2026 and 2027, the tax report itself drops away when revenue for the year is $2,650,000 or less, because no franchise tax is owed at that size. The short paper still goes in. Unless the Comptroller already parked the company on the skip list, that short paper is the public information report on Form 05-102, or the ownership information report on Form 05-167. An unfiled short paper can strip the company's privilege to operate here, including standing to bring a case or to answer one in a Texas court, and it can expose the people running the company on certain debts. A financial institution follows a different forfeiture rule, and that exception is read from the statute, not from memory.
Form 05-102 belongs to corporations, limited liability companies, limited partnerships, professional associations, and financial institutions that were organized in Texas or that have a Texas connection. The signature on it can come from an officer, a director, or someone else the company has authorized. Entities that are taxable and are outside that list send the ownership report instead, and the ownership details on that report stay confidential. There is no single information sheet for a combined group. Each member organized in Texas, or otherwise tied to the state, sends a report of its own. A year with a zero tax bill still gets the information report. Officers who change after this filing can wait until next year's report. Fix the filing later only if the original was wrong or the need is critical. A new registered agent is recorded with the Secretary of State, so Form 05-102 and Form 05-167 leave that change alone.
On the same 2026 and 2027 rows, the Comptroller prints 0.375 percent for a retail or wholesale business and 0.75 percent for other businesses. Each person can put no more than $480,000 of compensation into the deduction during 2026 and during 2027. A page aimed at 2026 leaves the 2024 dollar row alone. An older report year gets that older year's row, and we read the row before anyone types a figure.
Which pay counts, and when the short math is allowed
On the path that removes compensation, the pile includes W-2 wages and cash paid to officers, directors, owners, partners, and employees. Certain benefits can ride along, among them health care, retirement, and workers compensation. Payments reported on a 1099 stay out of that pile. Payroll taxes the company pays on its own stay out too. The cap per person is whatever figure the Comptroller's row shows for that report year. Pulling the W-2 wages in, and leaving the 1099 payments out, is the owner's call, and the books can show the call.
The shorter computation, the one labeled EZ, opens when annualized total revenue is at or under $20 million. The price of picking it is that the margin deductions go away. The rate printed for EZ in 2026 and 2027 is 0.331 percent. The long form is the one that has to be used when the company sits over the no tax due line and is not on EZ, and also when a margin deduction will be taken. The owner makes that call. We will name which facts in the books make one path honest and which facts make the other path honest. A services company will not be dressed up with a goods cost the books do not support.
Moving the May date
Nothing moves the May 15 due day unless the original day brings either the payment or a Comptroller form. In general the money sent with it is the whole prior year tax, or else ninety percent of the tax the current report will actually owe. A company that only became subject during the prior year is blocked from using the whole prior year amount on its first annual report. A company outside the electronic transfer rule can ask on Webfile or on Form 05-164, and the date that extension runs to is November 15. Once the previous state fiscal year shows $10,000 or more of this tax paid, later payments have to move by electronic transfer. For that payer, August 15 is where the first extension lands, and a second extension can run out to November 15. A payer at $500,000 or more asks by sending a timely TEXNET payment under code 13080, and that payer does not also send Form 05-164. Whether a TEXNET payment beat the cutoff depends on an hour the Comptroller prints. We look that hour up on the extensions page for the payment in front of us. A remembered hour stays off your file.
Read the late charges the way you would read a second sentence from the same speaker. A report that misses its day costs a flat $50. Tax money that arrives during the thirty days right after the due date picks up an extra 5 percent. Tax money still missing after those thirty days picks up 10 percent. A separate interest charge begins once 61 days have passed, and the percent for it lives on the Comptroller interest page, so this page leaves that percent there. When the company no longer has enough of a Texas connection, the final report has to be in no later than sixty days after that break. Winding the company up is the owner's call, and so is severing the Texas tie. The closing stack includes that final report and the Secretary of State certificate of account status. We read the Comptroller's closing instructions before we tell you which paper goes first.
Sales tax in the same close as the letter
A franchise letter is one way a messy month starts to feel official. Sales tax can do the same job inside the same close, and the two papers share the books. The state piece is 6.25 percent. A city can add a local piece, a county can, and a transit district can, each local piece capped at 2 percent. On any one sale the buyer tops out at 8.25 percent. Because the rate follows the place, the owner looks the address up on the Comptroller rate locator the same day the sale happens. Writing one city's percent onto this page would be a guess, so the percent stays on that locator.
Once the permit exists, the letter that comes with it tells the seller whether the rhythm is monthly or quarterly. A monthly filer sends the report on the twentieth, covering the month that just ended, which puts April's report on May 20. Quarterly sales tax goes out four times, in April, July, October, and January. Someone on a yearly rhythm sends one report for the year that ended, and January 20 is that report's day. If the sales-tax day falls on Saturday, Sunday, or a holiday, it moves forward to the next day the agency is open. On-time filing plus on-time payment can shave 0.5 percent off the sales tax due. Prepaying can earn that same 0.5 percent and an added 1.25 percent. A report that shows up late costs $50 on this tax too. The 5 percent add-on covers tax that arrives in the first thirty days, and the 10 percent add-on covers tax that is later than that. Interest on sales tax that is past due also waits until day 61, and its percent stays on the interest page.
A close that helps the next speaker separates four piles. Sales the shop made itself. Sales a marketplace made. Exempt sales that have a certificate in the file. Items pulled out of stock so the shop could use them. Where a marketplace already promised in writing to collect, those sales are reported inside total Texas sales and then removed from the taxable amount. The agency's reporting picture puts thirty thousand dollars of marketplace sales beside twenty thousand dollars of taxable sales from the seller's own site. The total line reads fifty thousand dollars. The taxable line reads twenty thousand dollars. Those dollars belong to the Comptroller's picture, not to a file we keep.
The resale certificate, told as a broom
Form 01-339 is the resale and exemption certificate, and a certificate filled out properly is what lets the seller show that a purchase was meant for resale. A permit number will not stand in for it. Copying the permit into the file still leaves the seller without Form 01-339. Form 01-339 stays with the sales records for four years, which is also how long gross receipts have to be kept. Tax comes due later if the buyer puts the item to the buyer's own use. The picture the agency uses is a broom that left the stockroom so someone could sweep the shop. Tax on that broom is figured as the fair market rental value for however long it was used that way, or else as the price paid to buy it, and the figure lands on the taxable purchases line. The broom is the agency's illustration. If resale is uncertain, Form 01-339 stays in the buyer's drawer. A blanket certificate is available when the customer buys for resale only, and when the certificate states that every purchase will be resold in the ordinary course. The agency's other picture is a service station handing over its certificate to buy a sofa. The seller pushes back when the item is something that business does not normally resell.
A place of business, in this rule, is a store or another spot where the people who sell take at least three orders in the calendar year, and those orders come from someone other than employees and affiliates. A website does not count as that spot. A server does not. An address on the internet does not. A software application does not. On an ordinary sale, the local piece tracks where the seller's place of business sits. On a use tax sale, the local piece tracks the spot where the customer first stores the item or first puts it to use. We keep those as two rules.
Selling from far away, and selling only on a marketplace
A remote seller whose Texas revenue across the prior twelve calendar months sits under $500,000 can skip both the permit and the duty to collect use tax. Marketplace receipts belong in the $500,000 test. They stay in the test when the marketplace was the one collecting. The agency's picture is three hundred thousand dollars on the seller's own site beside another three hundred thousand dollars on marketplaces. Six hundred thousand dollars together sits over the safe harbor. Collection then splits. The seller's own site is the seller's job to collect. Each marketplace collects on its own sales where it had already said in writing that it would. That pair of figures is the agency's picture.
A remote seller whose only channel is a marketplace, and who has taken the marketplace's written assurance in good faith, can skip the permit, and still keeps the marketplace records for at least four years. A person living in Texas whose only channel is a marketplace still has to hold a permit, because living in the state is a physical presence. Stock that sits briefly in a marketplace warehouse inside Texas does not, by itself, force a permit while the seller remains under the safe harbor and the provider had already said in writing that it would collect. Once the seller is over the line, the permit is required and collection starts. A company storing stock that way can also owe the franchise report. Both reports are fed by the same books.
Some remote sellers are offered one local use tax percent on Form 01-799. The Comptroller recalculates the single local percent on Form 01-799. On preparation day we read whatever figure is live. A percent remembered from last season stays out of your books. A seller who later falls below the dollar line and wants to stop collecting uses the Comptroller termination form. The rule for starting again sits on that same page, and we read it before we name a restart day.
The letter joins the person who spoke
The Comptroller letter does not shove the earlier speaker aside. It sits beside that speaker. A partner who watched one card pay the shop and the house in a single week is still pointing at that week. Where some of those charges were the shop collecting sales tax, the same week also shows whether that tax was set aside or whether it was spent. Charges that belong to the household come off the books. Charges that belong to the company stay, each one with a receipt or with a holding spot until the receipt shows up.
A preparer who cannot tie retained earnings to the net income that was filed is still pointing at those two figures. Revenue on the franchise report begins from the federal amounts, then applies the exclusions the statute names. Where the two figures disagree, the disagreement is the work. We will not mint a third figure so the federal return, the books, and the Texas report can pretend to be one number.
A lender letter is still read for its verb. A list that ties out to the bank is a close we can build, and a Texas filing can sit in that package as a date plus a copy. A signature that assures the statements is a different ask. An assuring signature is a request this practice turns down. Every word of that boundary is written on the disclosures page, which is the page to read before anyone asks for an assuring signature. The franchise report is a different paper from that assuring report. Getting the books ready so the report can be prepared is the work here. Putting an opinion signature on the statements is outside that work.
A buyer who asks for one closed month still receives one month a stranger can open. The month shows customer money, owner money, transfers, taxed sales, marketplace sales, and any item taken off the shelf for the shop's own use. Later months wait their turn. A speech about how hard the Comptroller was does not fill a hole in the path from the deposit to the profit.
A shop we made up, so you can hear the order
Picture a shop we invented for this page. The shop is a constructed hypothetical. The shop is not a client. The shop is outside the Comptroller's illustrations. The shop sits outside Dallas and outside Fort Worth. Yearly revenue is under $2,650,000, so the 2026 franchise tax report itself is not required, while the short information report still is. In March a partner says the card is a mess. In April a Comptroller notice names that information report. The notice is what makes the partner's comment feel official. The first check is still the partner's week, because that week is the part of the books that is actually tangled. The information report is the dated paper, and it goes in on time in a year when no franchise tax is owed. April's sales tax lands on the same calendar, due May 20. Payday stays with the owner. We can talk through how pay gets set up on the system the company already runs. After that setup conversation, payday is still something the owner runs.
Treat that shop as a teaching picture. It does not describe your file, and it does not bind what we will find when we open yours. Where revenue is over the line, the long form and the shorter computation are both real choices, and we will say which facts you actually have. Where a letter asks for an assuring signature, the answer on that signature is no, and a tie out of the numbers can still be yes. A call from the Hill Country, from the Gulf, or from the Panhandle is the same video call into the Dallas practice. Bring the sentence someone said, the role that person holds, and the notice. Leave a street address off the form.